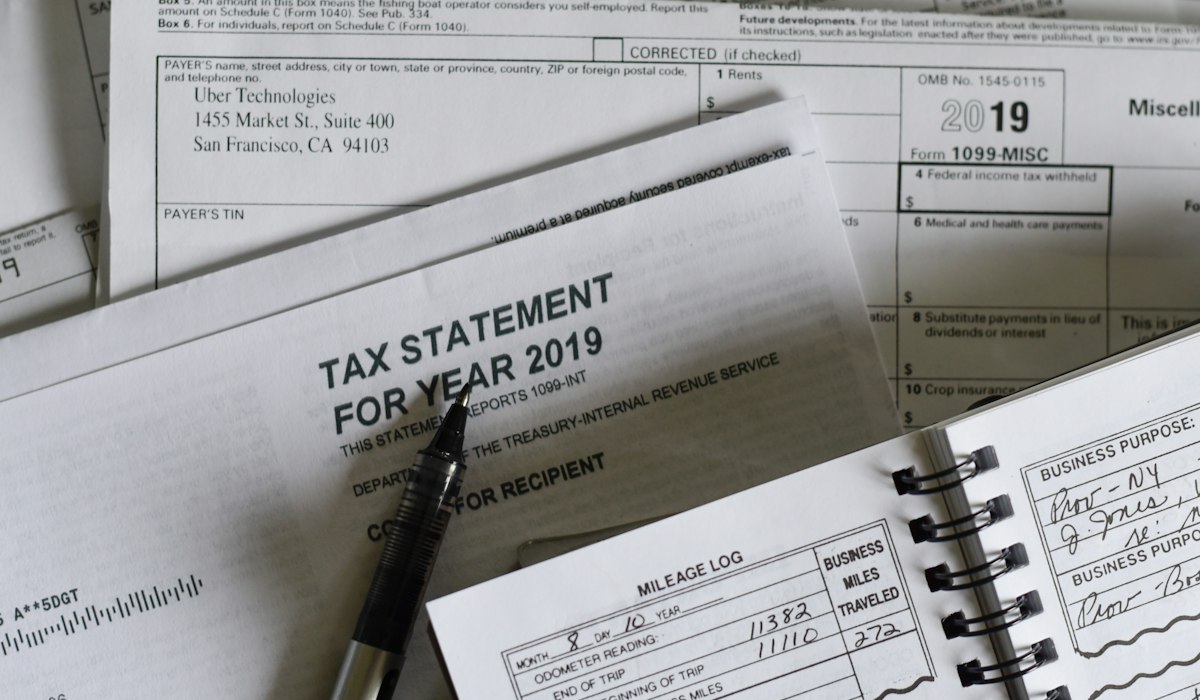
For many individuals, taxes are treated as an unpleasant annual ritual: gathering scattered receipts in April, filling out complicated forms under stress, and hoping for a refund.
However, reactive tax preparation is fundamentally different from proactive tax planning. Tax preparation merely records financial history; tax planning shapes it. By understanding legal tax codes and structuring your savings, investments, and expenditures strategically throughout the year, you can legitimately minimize your tax liability and retain more wealth.
Tax Avoidance vs. Tax Evasion: Knowing the Legal Line
Before exploring tax strategies, you must understand the distinction between legal optimization and criminal liability:
- Tax Avoidance: The completely legal optimization of your financial affairs to minimize tax liabilities using statutory provisions, credits, deductions, and exemptions provided by legislative bodies. In the words of renowned jurist Judge Learned Hand: “There is nothing sinister in so arranging one’s affairs as to keep taxes as low as possible.”
- Tax Evasion: The illegal, deliberate concealment of income, fabrication of deductions, or misrepresentation of financial facts to avoid paying taxes. Tax evasion carries civil penalties, interest charges, and criminal prosecution.
The Hierarchy of Income Taxation: How Brackets Function
A widespread misconception among employees is that moving into a higher tax bracket will reduce their take-home pay because “all my income gets taxed at the higher rate.”
Modern tax systems operate on Marginal Tax Brackets, not flat tax rates. In a marginal bracket system, your income is taxed in progressive slices:
| Tax Bracket Slice | Hypothetical Rate | How It Applies |
|---|---|---|
| First $11,000 | 10% | Only dollars 1 through $11,000 are taxed at 10% |
| $11,001 to $45,000 | 12% | Only dollars within this specific window are taxed at 12% |
| $45,001 to $95,000 | 22% | Only dollars within this specific window are taxed at 22% |
If you earn a $2,000 raise that pushes your top income from $44,500 to $46,500, only the $1,500 that spills over into the 22% bracket is taxed at the higher rate. Every preceding dollar remains taxed at the lower rates. A raise will never result in lower net take-home pay.
Harnessing Tax-Advantaged Accounts
The most potent tax-planning tool available to everyday wage earners is the strategic utilization of government-incentivized tax shelters:
1. Traditional Tax-Deferred Accounts (e.g., Traditional 401(k), IRA)
Contributions to traditional accounts are made with pre-tax dollars, directly reducing your taxable income in the current year. If you earn $80,000 and contribute $10,000 to a traditional retirement plan, your reported taxable income drops to $70,000. Your investments compound tax-free until withdrawal in retirement, where distributions are taxed as ordinary income.
2. Post-Tax Growth Accounts (e.g., Roth IRA, Roth 401(k))
Contributions to Roth accounts are made with after-tax dollars today, providing zero immediate tax deduction. However, all capital gains, dividends, and interest compound completely tax-free, and qualified withdrawals in retirement are 100% tax-free forever.
3. The Triple-Tax-Advantaged Health Savings Account (HSA)
If enrolled in a high-deductible healthcare plan, an HSA offers an extraordinary triple tax shelter:
- Contributions are 100% tax-deductible upfront.
- Investments inside the account grow tax-free.
- Withdrawals for qualified medical expenses are completely tax-free at any age.
Systematic Year-Round Record Keeping
The greatest tax deductions are frequently forfeited simply because taxpayers fail to maintain contemporaneous documentation throughout the year:
- Charitable Contributions: Keep written acknowledgment letters for donations exceeding $250, alongside bank proof.
- Home Office and Self-Employment Outflows: Track business mileage, utility splits, and equipment purchases contemporaneously via accounting software.
- Capital Loss Tracking: Maintain organized records of non-retirement investment purchases to offset taxable capital gains during annual tax filing.
Frequently Asked Questions
What is the legal difference between tax avoidance and tax evasion?
Tax avoidance is the 100% legal optimization of your financial affairs using statutory deductions, credits, and tax shelters provided by law. Tax evasion is the illegal concealment of income, fraud, or falsification of records to evade paying taxes.
Why is an HSA called the “Triple-Tax-Advantaged” account?
HSA contributions are 100% tax-deductible upfront, investments inside the HSA grow completely tax-free, and withdrawals for qualified medical expenses are 100% tax-free at any age.
How long should I keep tax records and deduction receipts?
Tax authorities generally recommend keeping tax returns, receipts, 1099s, and supporting documentation for at least three to seven years to substantiate claims in the event of an audit.
Tanisha
Tanisha specializes in practical personal finance, intentional saving strategies, household budgeting systems, and beginner-to-intermediate investment fundamentals. With a background in financial education and consumer economics, she translates complex wealth-building principles into actionable, step-by-step guides for everyday readers.
View all articles by Tanisha →